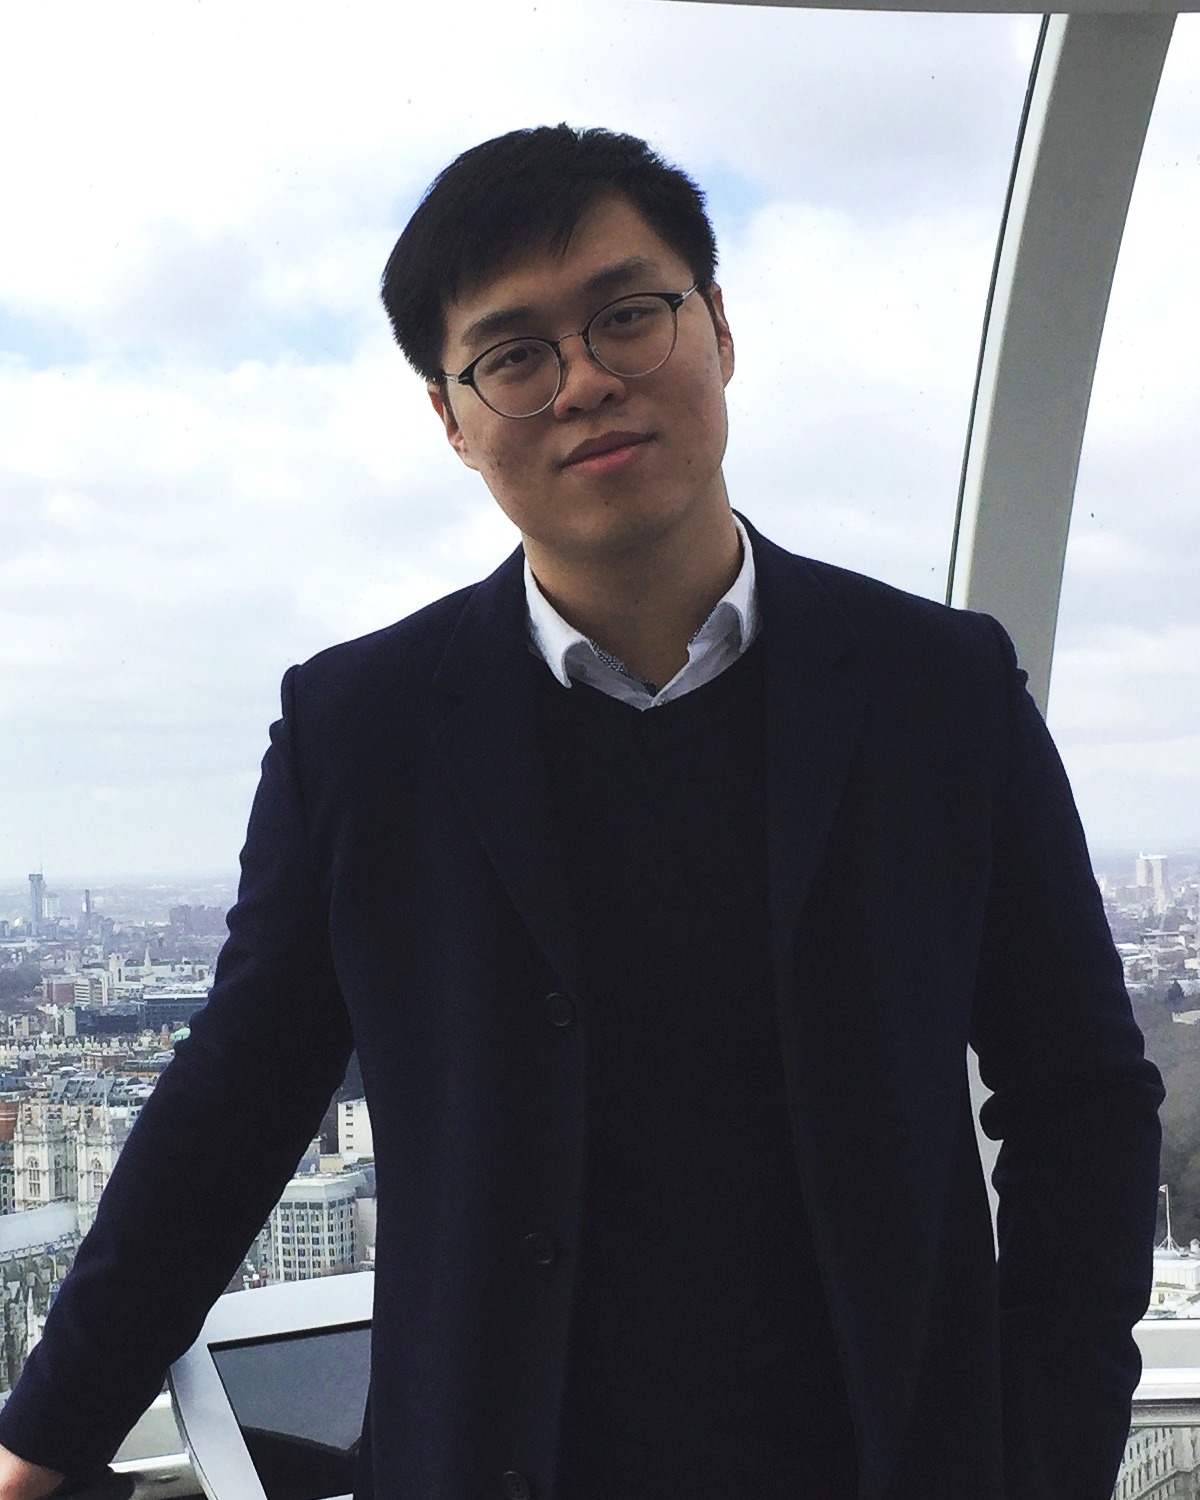
Portrait of Yue Wang

PhD in Economics

Yue Wang

Department of Economics, University College London

I am a PhD in Economics at University College London. My research is in macroeconomics, monetary economics, fiscal policy, international macroeconomics, and currency unions.

I study how fiscal instruments, household heterogeneity, and cross-border financial integration shape stabilization and risk sharing when monetary policy is constrained.

Research Fields

Primary: Macroeconomics; monetary economics; fiscal policy.

Secondary: International macroeconomics; currency unions; heterogeneous-agent New Keynesian models.

Contact

Department of Economics
University College London

yue-wang.19@ucl.ac.uk
+44 07933361798
@YueWang9838

Research

Working Papers

Working paper

Rule-Based Fiscal Stabilization with Consumption Taxes

Download paper

I study how far a consumption tax rule can substitute for interest rate policy when nominal rates are constrained. In a two-agent New Keynesian economy, the tax shifts spending across dates but also introduces labor supply distortions and affects tax revenue. Equilibrium determinacy depends jointly on transfer distribution and feedback strength. Weaker feedback improves population welfare under markup and productivity risk, while demand risk yields the highest welfare at an intermediate feedback strength. Inflation responds non-monotonically to consumption tax feedback strength, which can restrain inflation while producing different allocations and welfare from monetary policy.

Work in progress

Private Cross-Border Portfolios and Public Fiscal Risk Sharing in a Currency Union with Nominal Rigidities

This paper studies how private cross-border portfolios and public fiscal instruments interact as risk-sharing mechanisms in a currency union with nominal rigidities. I develop a two-country New Keynesian model with tradable and non-tradable goods, sticky non-tradable prices, endogenous international portfolios, and fiscal instruments. Households trade CPI-linked bonds and claims to non-tradable profits, making internal CPI differentials and relative marginal-cost risk the key hedging objects. The analysis derives a private-spanning benchmark and shows how domestic fiscal capacity changes relative-price dynamics and portfolio demand. Union-wide transfers matter for first-order allocations only when private markets fail to span relevant risks or domestic stabilization is incomplete.

Teaching

Teaching Experience

ECON0016: Macroeconomic Theory and Policy

Teaching Assistant, University College London

Oct. 2024 - Present

ECON0019: Quantitative Economics and Econometrics

Teaching Assistant, University College London

Oct. 2021 - Oct. 2024

CV

Curriculum Vitae

A current copy of my CV is available below.

Download CV